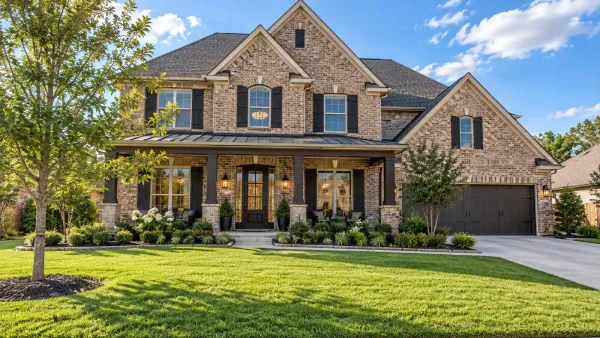

Builders in the Houston area are competing hard for buyers right now, and that works in a veteran’s favor. Where a conventional buyer often gets asked for a large cash deposit to start a build, VA buyers can frequently negotiate a much smaller earnest money amount. Stack that against closing cost assistance and rate buydowns builders are already offering, and it’s realistic to leave the closing table having spent close to nothing.
If you’re a veteran here in Houston, there’s a good chance you’re sitting on one of the greatest wealth-building tools in the country, and half of you aren’t using it because somebody gave you bad advice. Maybe a landlord. Maybe a seller who didn’t understand the loan. Maybe a random post online. That bad advice keeps good military families paying rent every month instead of building something that’s actually theirs.
I’m Miguel Gutierrez with Texas Homes Sold Group, and I’m an Army veteran myself. I’m not here to bore you with 50 pages of real estate math or turn you into a loan officer. I want to show you how this actually works in our market.
One thing about me that shapes how I approach this: staying active is a big part of my life outside real estate. You’ll catch me at a gym or out on a trail more than you’ll catch me in a suit. That connects to how I think about home buying, too. A house isn’t just square footage. It’s your home base. Somewhere close to a gym you’ll actually go to, trails you’ll actually use, the H-E-B you’ll be at every week, and a community that fits how you already live.
That’s the lens for everything below.
What the benefit actually gives you
A lot of veterans undersell their own benefits.
Zero down keeps your cash where it belongs. I’ve watched buyers dump every dollar of savings into a big down payment on a conventional loan. Sure, they own a house. Now they’re house rich and cash poor. No cushion, no breathing room. With the VA loan you can buy that same home and still walk away with $30,000, $40,000, even $50,000 sitting liquid for emergencies, for investments, for life. That flexibility matters more than people realize until they need it.
No monthly mortgage insurance, ever. Go conventional without 20 percent down and you’re paying somewhere around $150 to $200 every month just for PMI. FHA has its own version. VA skips it entirely. Instead there’s a one-time funding fee, and you’re exempt from that if you have a service-connected disability rating of 10 percent or higher. You can confirm through VA.gov.
That’s real money back in your pocket every month for as long as you own the home.
And they aren’t slow. VA loans close in about 30 to 45 days on average, right in line with conventional and FHA. When the file is handled right, full preapproval up front, documents in early, no delays on the appraisal, working with a lender who actually knows VA loans, 30 days is realistic and sometimes faster.
When it comes to actually winning a house in Katy, Richmond, or Sugar Land, presentation matters. My team makes sure that when a VA offer goes to a listing agent, they see it as fully underwritten and rock solid, not something to worry about. That’s what gets VA offers accepted in a competitive market. Not luck. I broke down more of these misconceptions in our VA loan myths article.
New construction is where veterans leave money on the table
This is the part I really want you to hear, because a lot of veterans miss it entirely.
With a lot of builders, conventional buyers are asked to put down a pretty significant cash deposit just to get the build started. As a VA buyer, you’re often able to negotiate a much smaller out-of-pocket earnest money amount instead.
And here’s the other half. Houston builders are competing hard for buyers right now. That means closing cost assistance, rate buydowns, sometimes even covering fees outright, all on the table just to earn your business.
Stack those together with your VA benefits and it is very realistic to walk away from that closing table having spent close to nothing out of pocket.
| Typical conventional buyer | VA buyer | |
|---|---|---|
| Builder deposit to start the build | Often a significant cash deposit | Often a much smaller negotiated amount |
| Down payment at closing | 3 to 20 percent | Zero |
| Monthly mortgage insurance | Yes, without 20 percent down | None |
| Builder incentives available | Yes | Yes, and they stack with VA benefits |
If you’re touring model homes, talk to me before you sign anything with the builder’s on-site agent. That agent works for the builder. Here’s more on buying new construction in Fort Bend County.
Where you land matters as much as how you get there
Out in Richmond, Fulshear, and Katy, you’ve got newer master-planned communities built around a lifestyle rather than just a house.
Harvest Green has a working farm and resident gardens. Cross Creek Ranch has fitness centers, pools, and miles of walking trails. These aren’t just subdivisions. They’re set up so your daily routine actually has somewhere good to happen.
When we’re looking at homes together, I’m not just showing you square footage. I’m showing you where your life is going to fit. You can read more about Richmond and Fulshear to get a feel for the differences.
Getting qualified is easier than you think
I know for a lot of guys and gals this is the part that feels like a headache before you even start.
You don’t need to go digging through boxes for your DD-214. Through the VA’s electronic system, a lender can typically pull your Certificate of Eligibility within minutes of you applying. It’s fast and it’s simple.
Beyond that, you don’t need to stress over underwriting guidelines or funding fee tables. My job is connecting you with lenders who live and breathe VA loans every day, so they handle the heavy lifting on the back end while we focus on the part that’s actually fun. The full sequence is laid out in our VA loan step by step guide.
One more thing, because language should never get in the way of understanding your own benefits. If Spanish works better for you or your family, we’ve got you covered at every step.
Rates, fees, and builder incentives change constantly. I’m a realtor, not a lender, so confirm your specific numbers with your loan officer before you plan around them.
Frequently Asked Questions
Can you use a VA loan on new construction in Houston?
Yes, and it often works better than buyers expect. Builders across the Houston area accept VA financing, and because they’re competing hard for buyers right now, VA benefits can be stacked with builder incentives like closing cost assistance and rate buydowns. The result is frequently a very low out-of-pocket purchase.
Do VA buyers pay less earnest money to a builder?
Often, yes. Many builders ask conventional buyers for a substantial cash deposit to start a build, while VA buyers can frequently negotiate a much smaller out-of-pocket earnest money amount. It’s a negotiation point, not an automatic benefit, so it helps to have an agent raise it before you sign the builder contract.
Can a builder pay your closing costs on a VA loan?
Builders in the Houston market commonly offer closing cost assistance, rate buydowns, and sometimes cover fees outright to win business. Combined with the VA’s zero down payment, veterans can realistically reach the closing table having spent close to nothing out of pocket. Specific incentives vary by builder and by community.
How much does no PMI save on a VA loan?
A conventional buyer putting less than 20 percent down typically pays around $150 to $200 per month in private mortgage insurance, and FHA loans carry their own version. VA loans have no monthly mortgage insurance at all, so that amount stays in your pocket every month for as long as you own the home.
How fast can a VA loan close in Houston?
VA loans average about 30 to 45 days, in line with conventional and FHA. When the file is handled correctly, with full preapproval up front, documents submitted early, no appraisal delays, and a lender experienced in VA loans, closing in about 30 days is realistic and sometimes faster.
How do you get a Certificate of Eligibility for a VA loan?
You don’t need to locate your physical DD-214 first. Through the VA’s electronic system, a lender can typically pull your Certificate of Eligibility within minutes of your application. It’s one of the faster steps in the entire process.
Can Spanish-speaking veterans get help with the VA loan process?
Yes. Language should not be a barrier to understanding a benefit you earned. Our team supports Spanish-speaking veterans and their families at every step, from the initial conversation through closing.
Let’s find your home base
You don’t have to figure this market out on your own. I’ve walked in your boots as an Army veteran, and I bought my own home using these exact steps, so when I tell you this benefit is worth using, that’s experience talking rather than a script.
You can also read more about using your VA loan benefit. Let’s talk through your goals and get you into the right place.